
Connect Now
Service & Support:
- Follow-up from a licensed broker within 24 hours
- Policy Review and Comparison
- Risk Assessment
- Help with certificates of insurance, policy changes and contract reviews
- Renewal planning well before your policy expires
Pollution Insurance Ontario
Pollution insurance (often referred to as pollution liability insurance or environmental impairment liability insurance) is designed to protect Ontario businesses from these environmental exposures that are commonly excluded from standard policies.CommercialInsurance.ca connects Ontario business owners with licensed brokers who can help identify real world pollution risks, arrange coverage that fits your operations, and support you if a claim happens. That is the difference between having a policy on paper and having protection you can rely on.
Get A Quote
How CommercialInsurance.ca works
We are not an insurer or a broker. We find you the right one.
Matched by industry
We connect you with a broker who works with businesses like yours, not a generic call centre.
Licensed Ontario brokers
Insurance brokers in Ontario are licensed by the Registered Insurance Brokers of Ontario (RIBO).
Fast follow up
Once we receive your information, a professional in our network will connect with you within 24 hours.
No cost to be matched
Our referral service is free for businesses. You deal directly with the broker for quotes and coverage.
Understanding Pollution Insurance
What is Pollution Liability Insurance?
Pollution liability insurance, also known as environmental impairment liability (EIL), is coverage that can help protect a business from third party claims and first party costs tied to pollution conditions connected to covered operations. Depending on the policy and how it is structured, it can respond to claims and costs involving bodily injury, property damage, environmental damage, cleanup, emergency response, and in some cases business interruption.
Pollution events can happen suddenly (for example, a spill from a tank during work) or gradually (for example, a slow leak that goes unnoticed). That matters because gradual pollution is one of the most common areas where standard coverage falls short.
Why it matters for Ontario businesses
Many Ontario businesses assume their commercial general liability policy will handle environmental damage. In practice, most CGL policies contain pollution exclusions, and even when a limited “sudden and accidental” option exists, it can be narrower than a dedicated EIL policy and may be restricted by detection and reporting timeframes.
Pollution risks can show up in more industries than people expect. Examples of common exposures include leaks from machinery or storage, project site runoff, spills during transport, and job site hazards like asbestos, mould, and dust.
Types of Pollution Insurance Available in Ontario
Pollution insurance is not one size fits all. Most Ontario businesses fit into one or more of these common structures, and the right approach depends on how your operations create exposure.
Commercial pollution liability insurance for premises
Premises pollution liability is designed for pollution releases at, on, under, or migrating from a location you own or lease. It commonly includes first party coverage for items like cleanup, emergency response, and business interruption, and third party coverage for cleanup costs, property damage, and bodily injury.
This is often relevant for businesses with:
Storage tanks or fuel handling
Chemical storage or use in operations
Manufacturing and processing exposures
Auto service and repair operations
Commercial property owners and operators with environmental exposures on site
Contractors pollution liability insurance
Contractors pollution liability applies when work performed by or on behalf of a contractor results in the release of a pollutant into the environment. It is typically built to protect both ongoing and completed operations and can include coverage for property damage, bodily injury, cleanup, legal defence, and regulatory fines (subject to policy terms).
This is often important for contractors whose work can create environmental exposures such as:
Excavation and grading
Plumbing and mechanical work
Restoration and remediation work
Landscaping and site services
General contracting where subcontractor activity can create environmental liabilities
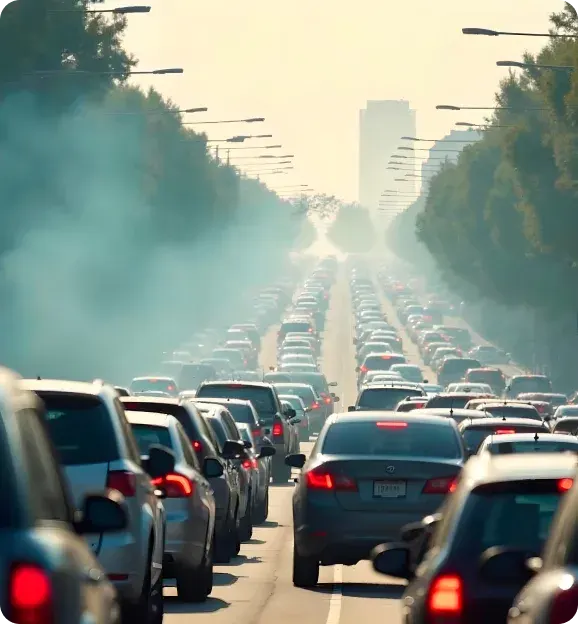
Transportation pollution liability
Transportation pollution liability is intended to address pollution exposures during loading or unloading and while products, materials, equipment, or waste are being transported, shipped, or delivered by your business or a carrier on your behalf. It is often offered as an optional coverage with premises or contractor pollution policies and may apply on a difference in condition basis when the pollution loss is not covered under the primary auto, marine, aviation, or rail liability policy.
This matters if you:
Move equipment or supplies between job sites
Transport waste or arrange for waste removal
Handle materials where a spill during transit could trigger cleanup and third party allegations
Specialized coverage options to consider
Beyond the core policy type, pollution insurance can often be tailored with options that match how Ontario businesses actually operate. Examples include:
Business interruption protection tied to a pollution event (varies by policy form and endorsements)
Coverage addressing unknown pre existing conditions under certain EIL structures
Emergency response costs and rapid mitigation support
Civil fines, civil penalties, and assessments where available (coverage depends on wording and jurisdiction)
The right mix depends on what you do, where you do it, and how your contracts allocate responsibility.
Get Your FREE Quote
Legal Requirements for Pollution Insurance in Ontario
Pollution insurance is usually not a blanket “you must buy it” requirement across all industries. However, Ontario businesses may have legal obligations that can create significant financial exposure after an incident, and contracts can require proof of environmental liability coverage.
Regulations and compliance
Under Ontario’s Environmental Protection Act framework, spills can trigger reporting duties. For example, anyone who spills a pollutant or has control of a spilled pollutant that causes or is likely to cause an adverse effect must notify the ministry, and a spill must be reported immediately when the person knows or ought to know it occurred and is causing or is likely to cause an adverse effect.
In practice, reporting can involve notifying multiple parties. A common framework described in Ontario spill reporting guidance includes notifying the Ministry of the Environment, Conservation and Parks, the municipality or region where the spill occurred, and others connected to ownership or control of the pollutant, along with the circumstances and steps taken to control the spill.
Ontario spill response reporting is time sensitive, and there is a 24 hour emergency telephone line used for spill reports as referenced in Ontario spill reporting procedures.
Consequences of non compliance
Failing to report promptly can create serious consequences, including potential fines and penalties depending on the situation.
Ontario’s spill liability framework may also operate on a strict liability concept in certain contexts, meaning responsibility can attach even where a spill was accidental.
This is one of the biggest reasons pollution insurance matters: it is not just about paying damages. It is also about having the financial and operational capacity to respond quickly, document properly, and continue operating while you deal with the incident.
Benefits of Having Pollution Liability Insurance
Financial protection against environmental claims
Pollution liability insurance is designed to address costs that can fall outside standard commercial policies. Depending on the structure, it can help with:
Cleanup and remediation costs
Emergency response expenses
Third party bodily injury and property damage allegations
Legal costs and defence where covered
Business interruption tied to a pollution incident in certain policy forms
Stronger reputation and easier contract compliance
Environmental events can create reputational harm and stakeholder scrutiny. EIL coverage is commonly positioned as a key tool to help manage the legal and reputational consequences associated with pollution events.
In addition, many businesses encounter insurance requirements in leases, vendor contracts, and project agreements. Having a broker that understands what those contracts are really asking for can prevent expensive gaps and delays.
How to Choose the Right Pollution Insurance Provider in Ontario
Key factors to consider
When a broker helps an Ontario business place pollution insurance, they typically start with the realities of your risk. Key factors include:

Where the exposure lives
One location, multiple locations, or changing job sites.

What materials you handle
Fuel, solvents, chemicals, waste, dust producing operations, and other potential pollutants.

How losses could happen
Sudden accidents, gradual releases, and unknown pre existing conditions all affect the coverage approach.

Transportation and disposal exposure
If you move materials or arrange disposal, transportation pollution extensions may be critical.

What your CGL excludes
Many businesses discover pollution exclusions only after an incident. The right solution is to identify those gaps before you are in a claim scenario.
Questions to ask potential insurers or brokers
Here are practical questions that help you avoid common gaps:

Is this premises coverage, contractor coverage, transportation coverage, or a combination?
Does it address sudden and gradual pollution events?
Are cleanup and emergency response costs included, and how are limits applied?
Is business interruption covered, and what triggers it?
Does the policy include any coverage for civil fines or penalties where permitted, and what conditions apply?
What exclusions could still apply (non compliance, known conditions, misrepresentation, deliberate dumping)?
What does the carrier expect from you in the first hours of an incident (reporting, mitigation, documentation)?
Why Ontario businesses choose CommercialInsurance.ca
Pollution risk is technical, and the difference between “covered” and “not covered” often comes down to details that are easy to miss.
Customers choose CommercialInsurance.ca because:
 1
We understand the risks before there is a loss.
We take time to understand your operations, contracts, and where pollution exclusions typically hide.
Get Started Now! 2
We focus on coverage that actually responds.
Our job is not just to get you a policy. Our job is to make sure your pollution insurance is structured to match how your business works today and how it will work as you grow.
Get Started Now! 3
Brokers know the Ontario market and who to approach.
Pollution and environmental liability is a specialized line. Experienced brokers know which carriers and programs fit different risk profiles, from contractors to property operations to transportation exposures.
Get Started Now! 4
Your broker advocates in the claim process.
If you ever need to make a claim, you want a broker who knows the policy, knows the market, and goes to bat for you.
Get Started Now! 5
We respond fast.
A professional in our network follows up within 24 hours. Environmental incidents do not wait, and neither should you.
Get Started Now!
If you want a pollution insurance quote in Ontario, or you want us to review your current policies for gaps, reach out to CommercialInsurance.ca and we will connect you with a licensed broker who can explain what you have, what you do not have, and what to do next.
Frequently Asked Questions
What does pollution insurance cover?
Pollution insurance can cover third party claims and first party costs tied to pollution conditions, such as bodily injury, property damage, environmental damage, cleanup, and emergency response. Some policy forms also include business interruption. Coverage depends on the policy type (premises, contractors, transportation) and the wording.
Does commercial general liability insurance cover pollution claims?
Often, no. Many CGL policies include pollution exclusions, and even when a limited “sudden and accidental” option exists, it can be narrower than a dedicated environmental impairment liability policy and may have strict time limits.
What is the difference between pollution liability insurance and environmental impairment liability insurance?
In many contexts, they refer to the same category of coverage. Environmental impairment liability is commonly used as an umbrella term for pollution related coverage that can include premises, contractor, and transportation policy forms.
Who needs pollution liability insurance in Ontario?
Any business exposed to pollutants or environmental hazards should consider it, especially contractors, property operators with environmental exposures, and businesses that transport materials or waste.
Is pollution insurance required in Ontario?
There is not a single rule that requires every business to buy pollution insurance. However, Ontario businesses may face strict spill reporting and cleanup obligations, and many contracts (leases, project agreements, vendor requirements) can require proof of environmental liability coverage.
What should I do if my business has a spill or pollution incident?
Prioritize safety, contain what you can without creating risk, and report as required. Ontario spill reporting guidance describes immediate reporting duties in certain situations, and prompt documentation is critical. Then contact your broker as soon as possible so the claim can be reported properly and the right response resources can be coordinated.
How much does pollution insurance cost in Ontario?
Pricing depends on your industry, operations, revenues, loss history, materials handled, locations, and the coverage structure (premises, contractors, transportation). The most effective way to determine cost is to have your exposures reviewed and quotes compared across the right markets.
Protect your team too
Offer health, dental and life benefits your employees will value.
We also connect Ontario businesses with licensed benefits advisors, from two person teams to growing companies.
 5/5 rating on Google
The Commercial Insurance Difference: Feedback from those referred
Proactive Broker Relationship.
The most noticeable difference was the fact that I no longer felt that I was needed to manage the broker... the brokers came to me with proactive recommendations and knew when to push and shop the market and when not to. When the topic of business insurance comes up, I always refer fellow business owners.
Steve T
Security Blanket For My Business
I was always the type of customer that never believed in insurance and only really got it because I had to. Then I connected with a broker through Commercial Insurance.ca and they asked me questions no one else ever did and that's how I knew something was different. They took the time to understand and evaluate the risks. Well, I ended up getting some extra coverage (legal expense) and thank goodness I did. Something fairly innocent turned into something quite nasty and I didn't have to do too much... my coverage took care of it. Now I look at Insurance as a security blanket for my business.
Michael L
They had my back
No one likes buying insurance because it's a bit of a bet against yourself. You just hope that when the bad things happen that insurance will do what it said it would do in the first place. Their specialist stand behind the policy's that they bind. They never professed to get me the best price, but they did say they have my back, and have my back, they did.
Steph P